Differences between income from labor remuneration, royalties, withholding, prepayment and final settlement
In 2019, the work of personal income tax comprehensive income settlement has been successfully completed. This year is the first time in the history of our country to implement the annual tax settlement. Many taxpayers have a better understanding of the taxation method of wages and salaries in comprehensive income, but they are right.Remuneration for labor services, remuneration for manuscripts and royaltiesThere is relatively little knowledge about how to tax the three incomes, especially the differences between the withholding, prepayment and final settlement of these three incomes. Let’s take a look together.
one
The calculation method of income is different.
When withholding and prepaying, the income from labor remuneration, royalties and royalties is the balance after deducting expenses from each income. Among them, "If the income does not exceed 4,000 yuan each time, the deduction of expenses shall be calculated according to 800 yuan; If the income is more than 4,000 yuan each time, the deduction will be calculated at 20% of the income. " The amount of income from remuneration shall be reduced by 70%.
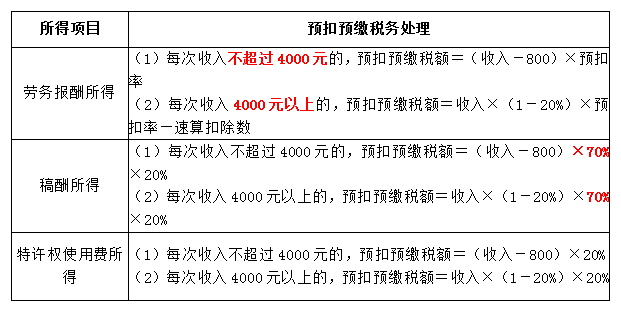
At the time of annual settlement, the income from labor remuneration, manuscript remuneration and royalties is the balance after deducting 20% of the expenses from the income. The amount of income from the remuneration is also reduced by 70%.
2
The applicable tax rate and withholding rate are different.
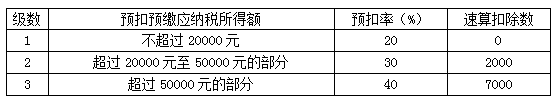
When withholding in advance, the withholding rate of 20% shall apply to the income from remuneration and royalties. Income from labor remuneration is subject to the three-level progressive tax rate of 20%-40%.
Personal income tax withholding rate table (applicable to withholding and prepayment of income from individual labor remuneration of residents)
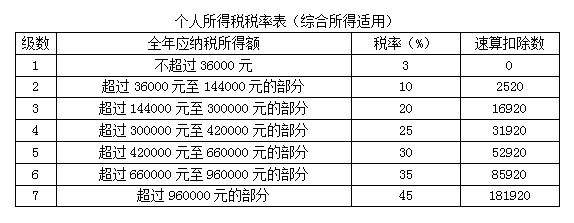
When the annual settlement is made, the income from labor remuneration, royalties and royalties shall be incorporated into the comprehensive income, and the excessive progressive tax rate of 3% to 45% shall apply.
three
The deduction time of public welfare donation is different.
Individual residents who obtain income from labor remuneration, royalties and royalties shall not deduct public welfare donation expenses when withholding and paying in advance, but shall be deducted when settling accounts.
Policy basis:
1. Individual Income Tax Law (Decree No.9 of the President of the People’s Republic of China)
2 "Regulations for the Implementation of the Individual Income Tax Law" (the State Council Decree No.707th)
3. Announcement of the Ministry of Finance and the State Administration of Taxation on Relevant Policy Issues Concerning the Settlement and Payment of Individual Income Tax Comprehensive Income (Announcement No.94 of the Ministry of Finance and the State Administration of Taxation in 2019)
4. Announcement of the Ministry of Finance and the State Administration of Taxation on Individual Income Tax Policies for Donations to Charity (Announcement No.99 of the Ministry of Finance and the State Administration of Taxation in 2019)
5. Announcement of State Taxation Administration of The People’s Republic of China on Handling the Settlement and Payment of Comprehensive Income of Individual Income Tax in 2019 (State Taxation Administration of The People’s Republic of China Announcement No.44, 2019)
Production team of this issue
Producer | State Taxation Administration of The People’s Republic of China Zhuhai Taxation Bureau Office
Graphic editing and distribution| Pearl tax financial intermediary
Source of manuscript| china taxation news
Reporting/feedback